QRIS Revolution: How Digital Native Gen Z is Redefining Indonesia’s Financial Landscape Through Cashless Transactions

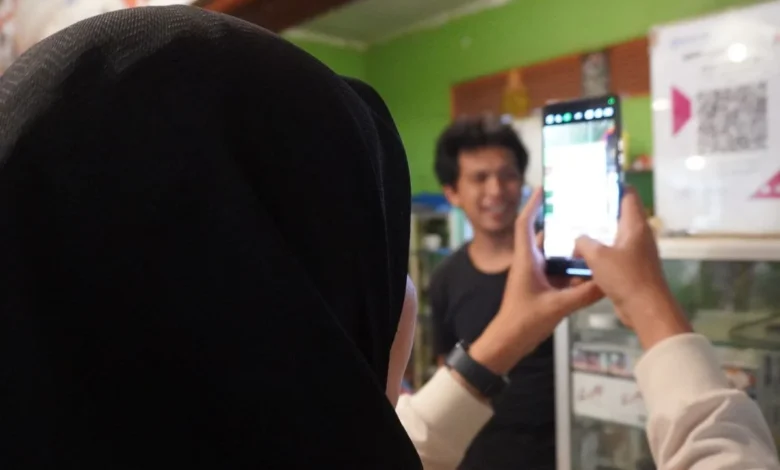
The rapid evolution of Indonesia’s financial technology sector has reached a pivotal junction, driven primarily by the shifting consumption patterns of Generation Z, a demographic defined by its status as digital natives. In an era where speed, convenience, and seamless integration are prioritized, the traditional reliance on physical currency is rapidly waning. At the heart of this transformation is the Quick Response Code Indonesian Standard (QRIS), a standardized payment gateway introduced by Bank Indonesia (BI) that has transcended its original utility to become a defining cultural and economic pillar for young Indonesians. This shift marks a significant departure from conventional banking habits, signaling the maturation of Indonesia’s digital economy.
The Genesis of QRIS: A Strategic Milestone
To understand the dominance of QRIS, one must look back at its inception. Launched by Bank Indonesia on August 17, 2019, the initiative was designed to address the fragmented nature of the digital payment ecosystem in Indonesia. Before the arrival of the standardized QR code, merchants were often forced to display a cluttered array of QR codes from various e-wallet providers, leading to confusion and operational inefficiency. By unifying these disparate systems into a single, interoperable standard, Bank Indonesia effectively lowered the barriers to entry for both consumers and micro, small, and medium enterprises (MSMEs).
The rollout was not merely a technological upgrade but a structural reform. By mandating interoperability, BI ensured that a user of any participating mobile banking application or e-wallet could scan any QRIS-enabled merchant code. This "one-for-all" approach created an immediate network effect, which Gen Z, with their inherent comfort with cross-platform digital tools, quickly adopted as the standard for daily transactions.
Why Gen Z Leads the Digital Charge
For Generation Z—individuals currently aged between approximately 12 and 27—the preference for QRIS is rooted in a psychological and practical alignment with their lifestyle. Research suggests that this cohort places a high premium on "frictionless" experiences.
- Efficiency and Time Management: In a fast-paced urban environment, the seconds saved by avoiding physical cash handling—such as waiting for change or managing coins—accumulate into a significant improvement in daily productivity. The transaction flow, which involves a simple scan-and-confirm process, aligns perfectly with the "instant gratification" model that defines digital-native behavior.
- Universal Compatibility: Gen Z is known for managing multiple financial identities. Whether they use a traditional bank app or a specialized fintech e-wallet, QRIS provides a uniform experience. This flexibility prevents the frustration of being unable to pay at a specific vendor due to application mismatch, a common pain point in the pre-QRIS era.
- Pervasive Accessibility: The ubiquity of QRIS is perhaps its strongest asset. It is no longer restricted to luxury retail or high-end malls. From street food vendors and local markets to independent boutiques and large-scale music festivals, the QRIS sticker has become a ubiquitous symbol of modern Indonesian commerce. This accessibility allows Gen Z to live entirely cashless, which is increasingly viewed as a sign of financial maturity and modern identity.
- Data-Driven Financial Awareness: Unlike cash, which leaves no digital footprint, every QRIS transaction is recorded within the user’s mobile banking history. This allows young users to track their spending patterns, set budgets, and exercise better financial discipline. This "automatic ledger" feature has become an essential tool for those attempting to navigate the complexities of personal finance in a consumer-driven economy.
Statistical Growth and Market Penetration
The numbers support the observation of a radical shift in payment behavior. Bank Indonesia’s data consistently highlights a year-on-year surge in both transaction volume and merchant adoption. By 2026, the volume of digital transactions processed via QRIS is projected to reach unprecedented levels, with many industry analysts citing it as the primary engine for non-cash transaction growth in the country.
Reports from regional branches, such as the notable 2.9 million transactions recorded in Bangka Belitung, serve as a microcosm for the national trend. This level of adoption in secondary regions indicates that the QRIS ecosystem is not merely a metropolitan phenomenon but is deeply embedded in the national economic fabric. Furthermore, large financial institutions have publicly acknowledged that QRIS is the "backbone" of their digital transaction strategies, underscoring its importance to the long-term viability of the national banking sector.
Official Perspectives and International Expansion
Bank Indonesia has maintained a proactive stance in expanding the utility of the QRIS network. Recognizing the success of domestic implementation, the central bank has begun exploring cross-border QRIS payment capabilities. By establishing bilateral agreements with countries such as Thailand, Malaysia, and Singapore, and currently exploring potentials in the Middle East and Australia, Indonesia is positioning its digital payment standard as an international asset.
For the Indonesian diaspora and younger travelers, the ability to use the same familiar interface in foreign markets is a significant milestone. This internationalization of QRIS serves a dual purpose: it facilitates tourism and commerce for Indonesians abroad, and it reinforces the credibility of the Indonesian digital payment framework on a global stage.
The Socio-Economic Implications
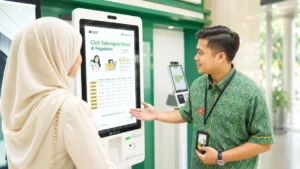
The transition to a cashless society, driven by Gen Z, carries profound implications for the Indonesian economy. The shift facilitates greater financial inclusion. By enabling small merchants to accept digital payments without the need for expensive Electronic Data Capture (EDC) terminals, QRIS has effectively "banked the unbanked." These small businesses can now generate a digital transaction history, which, in turn, makes them eligible for formal credit and financial products—a transition from the informal to the formal economy that was previously inaccessible to many.
However, this transition is not without its challenges. Cybersecurity and data privacy remain the primary concerns for regulators and consumers alike. As the nation moves toward an increasingly digitized financial system, the resilience of the infrastructure against cyber threats and the protection of user data have become paramount. Bank Indonesia and the Financial Services Authority (OJK) have implemented strict guidelines to ensure that as the ecosystem expands, security measures evolve in tandem.
Challenges to Continued Growth
While the trajectory is positive, several factors could influence the pace of adoption. The reliance on internet connectivity remains a limiting factor in remote or underdeveloped areas. Additionally, the digital literacy gap between different generations means that while Gen Z is spearheading the movement, sustained national growth requires broader education initiatives to ensure older demographics are not left behind.
Furthermore, the competition among e-wallet providers is intense. While QRIS provides the technical standard, the user experience is ultimately dictated by the quality of the banking or e-wallet application used. Firms are currently engaged in a race to provide the most intuitive interface, the most attractive loyalty programs, and the most robust security, all of which contribute to a healthy, competitive market that ultimately benefits the consumer.
Looking Ahead: The 2026 Horizon and Beyond
As Indonesia moves toward 2026, the role of QRIS appears cemented as the primary infrastructure for the nation’s digital future. The integration of artificial intelligence into banking applications will likely further refine the "financial awareness" aspect of QRIS, offering users personalized insights and automated financial management tips based on their transaction history.
The cultural shift represented by this change is equally significant. The "Gen Z" way of interacting with money—treating it as a series of digital entries rather than physical assets—is becoming the new standard for the Indonesian public. This generational shift ensures that the cashless ecosystem is not a passing trend but a permanent restructuring of the national economy.
In conclusion, the rise of QRIS is a testament to the synergy between technological innovation and demographic shifts. By providing a secure, efficient, and universally accessible payment method, Bank Indonesia has empowered a generation to take control of their financial lives. As the system continues to mature and expand beyond national borders, the QRIS model stands as a powerful example of how digital infrastructure can catalyze economic growth and social inclusion, setting a benchmark for other emerging markets to emulate in the years to come. The era of the digital wallet has arrived, and for Indonesia, it is clearly just the beginning.
Related posts: